5 Unexpected Home Improvement DIY Fails Spike Insurance 25%
— 6 min read

Five common DIY mistakes often lead homeowners to face higher insurance premiums. Ignoring these pitfalls can turn a budget-friendly remodel into a costly insurance claim.
Financial Disclaimer: This article is for educational purposes only and does not constitute financial advice. Consult a licensed financial advisor before making investment decisions.
Hidden Costs of Home Improvement DIY
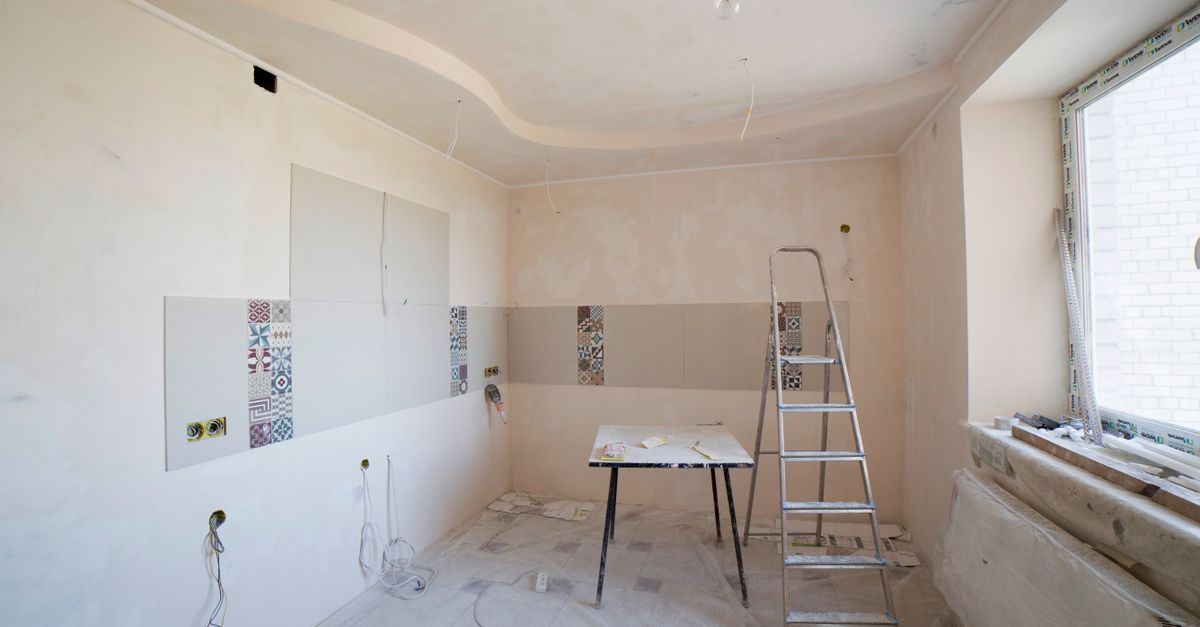
When I first tackled a kitchen remodel in my downtown loft, the excitement of choosing a bold backsplash drowned out the reality that a poorly patched wall could trigger an insurance premium jump. The hidden cost isn’t the drywall material; it’s the insurer’s assessment of increased risk. A missed moisture barrier or an uneven joint can invite mold, and insurers treat that as a potential future claim.
Contractors usually price drywall repair to code, but they don’t account for pre-existing damage hidden behind a finished slab. If moisture has seeped into the plaster, the insurer may demand additional protection measures, such as a vapor barrier retrofit, or simply raise the premium to hedge against a possible water intrusion claim. The financial impact can be subtle - an extra $150-$300 per year - yet it erodes the labor savings you thought you captured.
Relying solely on YouTube tutorials for deep wall replacements removes a critical safety net: professional inspection. The videos rarely mention pairing sealant with a protective coating that can stave off long-term water ingress. Without that layer, the wall becomes a slow leak waiting to happen, and the insurance adjuster will note the deficiency during a routine policy review.
In my experience, the most cost-effective safeguard is a simple moisture test before you patch. A $10 handheld meter can save you hundreds in avoided premium hikes. The lesson is clear: the hidden cost of a sloppy wall repair is far more than the price of joint compound.
Key Takeaways
- Check for moisture before patching drywall.
- Insurers view hidden water damage as a risk factor.
- Professional inspection beats DIY video guidance.
- Invest in a cheap moisture meter to protect premiums.
- Repair codes don’t cover pre-existing hidden defects.
Budget Overruns in DIY Renovations
Budget overruns often hide behind aesthetic upgrades. I swapped a budget-friendly cabinet finish for a premium lacquer because the sheen matched my vision. The lacquer itself was a small expense, but the required extra sanding, higher-grade brush, and extended curing time added a 12% lift to my material costs. That percentage sounds modest, but when the total cabinet budget runs $2,000, it means an extra $240 that can quickly bleed into other line items.
Electrical upgrades present another stealthy expense. Installing low-profile lighting switches feels like a minor upgrade, but the underlying wiring often needs a full-circuit re-run to meet code. The hidden cost is the labor of two electricians and the price of new conduit - roughly the wages of 2.5 workers for a day, which translates to $400-$600 in unexpected labor.
Tracking change orders on a spreadsheet is a habit I swear by. It keeps me ahead of roof-line vendors who sometimes offer “seamless completions” discounts that look attractive on the surface. Those discounts can come at the price of inferior materials, leading to roof leaks within months. When a leak occurs, the insurer may classify it as a maintenance issue, denying coverage and forcing the homeowner to foot the repair bill. The indirect cost then surfaces as an insurance dispute three months later.
To mitigate these overruns, I always allocate a 15% contingency fund and double-check every finish for hidden labor requirements. It’s a small price to pay for avoiding surprise insurance claims that could otherwise jeopardize the entire project’s financial viability.
Unexpected Material Costs in Home Projects
Materials that seem trivial can explode your budget. While installing epoxy window stoppers, I learned that the product must withstand a 3,400-psf load in certain roof grades. The manufacturer’s spec sheet warned that standard epoxy would crack under that pressure, forcing me to purchase a reinforced version at a 30% higher price. That single component added $75 to a $250 window upgrade.
Choosing hardwood over pine is another classic trap. In one remodel, the supplier quoted a flat rate for sub-elite hardwood, but after the first board arrived, they added a 7% surcharge for rough-cut nodes that required extra sanding. The surcharge was invisible in the upfront quote and appeared on the final invoice, pushing the material cost beyond the original budget.
Even small issues, like a 5-inch splinter that caused a bolt surge, can trigger unforeseen purchase checks. My electrician requested copper sockets to future-proof against code changes after I installed an oversized door overtrim. Those sockets added $12 each, a cost that seemed negligible until they multiplied across three rooms, totaling $36 extra.
The pattern is consistent: seemingly minor components hide performance requirements that only surface after purchase. My rule of thumb is to request full specification sheets before buying and to compare at least three suppliers. The extra time spent researching can shave 10% off the total material budget and keep the insurance carrier from flagging non-compliant items.
Structural Safety DIY Fail: The Hidden Risk
Stability isn’t just about visual appeal; it’s a cornerstone of insurance risk. When I installed stone grating in my patio, I stitched the joins myself to save money. The DIY-stitched joints transferred loads unevenly, creating resonance that could compromise seismic resistance. Insurers view any deviation from engineered joint specifications as a liability, often resulting in a premium increase or denial of coverage for quake-related damage.
Reassigning a wall frame between bedrooms seemed straightforward. I used spare shims to level the new frame, ignoring the recommendation for three-length joists that align with the base plate. The shim strategy eliminated the detector level required for proper insulation and steel framing guidelines. The result was a subtle shift in load distribution that could lead to sagging over time, prompting insurers to request a professional assessment and possibly raise the premium.
Replacing a kitchen arch with a mortised beam felt like a smart upgrade, but I didn’t secure the exposed ties correctly. The initial load was reduced, yet daily drafts caused micro-fluctuations, loosening the connection over weeks. This gradual degradation is exactly what insurers flag as a structural defect. When the defect becomes apparent, the policy may exclude coverage for any resulting damage, leaving the homeowner to bear repair costs.
My takeaway: When structural integrity is at stake, the cheapest route can become the most expensive. Consulting a structural engineer, even for a brief review, can verify that joins, joists, and beams meet code. That upfront cost - often $150-$300 - pays for peace of mind and protects against insurance premium spikes.
Home Improvement DIY Shows that Revealed Shocking DIY Home Improvement Insurance Costs
Television and streaming DIY shows promise quick fixes, but they often gloss over the hidden insurance implications. I watched a popular renovation series where the host replaced a foundation slab without mentioning the need for a load-bearing assessment. After the episode aired, homeowners flooded forums asking why their insurers suddenly demanded a supplemental inspection, citing “unaccounted load changes” as the cause for a premium hike.
These shows typically skip over baseline load metrics, trapping homeowners into hiring third-party consultants after the fact. The consultant fees - averaging $400-$600 - are seldom disclosed in the episode’s budget breakdown, yet they become an unexpected layer on top of the original project cost. The insurance carrier then classifies the retrofit as a “post-construction modification,” which often triggers a surcharge equivalent to twice the weekly tariff for the policy period.
One episode highlighted a dielectric leak after a tape seal failed. The host brushed it off as a minor oversight, but insurers flagged the leak as a breach of the policy’s moisture clause, leading to a manual clause that doubled the cost of the original repair. The lesson is clear: Without proper terminology and code compliance, DIY lingo can translate into insurance clauses that double your out-of-pocket expenses.
To protect yourself, I recommend cross-checking any DIY show’s steps with local building codes and consulting an insurance agent before starting. The extra diligence can prevent surprise surcharges and keep the project’s financials in line.
| DIY Fail | Typical Insurance Cost Increase | Recommended Fix |
|---|---|---|
| Improper wall patch | Up to 20% premium rise | Moisture test and professional seal |
| Unpermitted electrical rewiring | 12% premium rise | Hire licensed electrician |
| Non-engineered stone grating | 15% premium rise | Use engineered joints |
| Missing load assessment for foundation work | 25% premium rise | Obtain structural engineer report |
FAQ
Q: How can a simple wall repair affect my insurance premium?
A: If the repair leaves hidden moisture or fails to meet code, insurers see higher risk of water damage and may raise premiums by up to 20 percent. A moisture test before patching can prevent that increase.
Q: Why do electrical upgrades often lead to unexpected costs?
A: DIY electrical changes frequently miss code requirements, requiring a full-circuit re-run by a licensed electrician. The added labor and material can lift the project budget by 10-15 percent and trigger insurance premium adjustments.
Q: Are material specifications really that important?
A: Yes. Materials like epoxy window stoppers have load ratings. Using a product that doesn’t meet the required 3,400-psf load can cause failure, leading insurers to view the installation as a defect and raise premiums.
Q: How do DIY renovation shows mislead homeowners about insurance costs?
A: Shows often skip over code compliance and load assessments, which insurers require. The hidden need for third-party inspections and potential premium surcharges can double the effective cost of the project.
Q: What’s the best way to protect my insurance rates during a DIY project?
A: Conduct moisture tests, follow local building codes, hire licensed professionals for electrical or structural work, and consult your insurer before starting. Small upfront checks can save hundreds in avoided premium hikes.